|
With any monetary transaction like a loan to a friend, invoice from a business, or a refund from a tradesperson, there will always be a chance that the other party will fail to pay you.
Just getting back what is owed to you can be difficult enough, but if you then also lose touch with the debtor, the complexity of your problems will increase significantly. When a business owes you money it's generally a straightforward matter to track them down, as when a business is still trading their contact details can be found online or via their advertising. But for debts owed by a person it can be a much more difficult task to trace an individual. Regardless of having the debtor's mobile number, email address and social media details, the most important information you will need when considering legal action is their address. 
Legal options for debt recovery.
The first stage in taking formal debt recovery legal action is sending a Letter of Claim (also known as a Letter Before Action) to the debtor.
The purpose of this letter is to outline the exact amount that is owed, the reason you believe the debt is due, provide a reasonable timeframe for payment to be made in full, and in the event payment is not received in this timeframe, warn that court proceedings may be started without further notice. The Letter of Claim should be posted to the debtor at their current address. While a copy can also be sent via email it must be sent in the post and be clearly dated. Sending this letter is an important 'pre-action' step and is required to comply with the various pre-court action protocols. Should the letter not result in payment the next stage is issuing court proceedings. Again, this will require the debtor's current address for the court to successfully serve the Claim Form and for you to start any subsequent enforcement action. Therefore, finding the current address of the debtor is critical before considering legal proceedings. How to find a business that owes you money?
Businesses are generally easier to locate an address for, as most businesses want to be found by their potential customers. Their trading address will usually be on their website, used in their advertisements or documented in any agreements or terms and conditions you may have been given.
Failing these checks, the next places to try to locate an address are on the various business listings that are available online:
How do I find a person who owes me money?
Individuals can be much more difficult to locate an address for as there will be significantly less information about them online or in the public domain.
A first step is to ask any friends or business associates that you may have in common if they know the debtor's current address. Note that while you may know the workplace of the individual, legal correspondence for a debt owed by them personally must be sent to their residential address and not to their employer or place of work. There are then some free and low cost directories available online which may help trace an individual such as the BT Phonebook and 192.com. However, the results provided by these directories may be limited and outdated so it is not recommended that these are solely relied on. You may also be able to access and check your local council's open register. Investigators and tracing agents.
The most reliable method of tracing an individual's address is to instruct a professional tracing agent. These can be found online and will offer various tracing packages depending on the depth and timeframe required for the search. Also, many tracing agents offer a no trace no fee service which can be helpful in the event an individual cannot currently be located.
However when trying to locate an individual it is important to stay compliant with data protection and privacy laws. So ensure that any investigator or tracing agent that you instruct is an accredited firm. What if you can't find an address for the debtor?
If you've tried all of the above and still can't locate a business or residential address, your options will now be limited.
However it is worth bearing in mind that you generally have six years to start court proceedings on an outstanding debt. So there is nothing stopping you repeating the above searches every few months to see if the debtor resurfaces. Tracing someone who owes you money.
Being owed money but having no address for the debtor adds a further level of complication to taking legal action. However, with a little DIY investigation work and perhaps paying a small fee for some professional tracing assistance, most debtors can be found.
Once you have located the debtor you then need to be confident that they have the assets or funds available to repay the debt. If you were struggling to locate a business because it has closed, or an individual has moved due to their previous home being repossessed, you will need to think carefully about your chances of recovering the debt before incurring the cost of pursuing them through the courts.
Comments
Whether you are a business or an individual, when money is owed to you there's usually a clear deadline specified for when payment is expected to be made. For example, your business invoices will have a payment period detailed on them, and if you've loaned money to a friend then you will have an agreed repayment date or schedule.
But if this date passes and no payment has been forthcoming, can you claim interest on the money owed to you? 
When can you claim interest on a debt?
Your legal right to charge interest on an outstanding debt depends on a few factors which we'll cover in this guide. These include:
But if you are in any doubt whether you can charge interest on the money that is owed to you, you should seek legal advice from solicitors that specialise in debt recovery. Interest on business debts.
The ability to charge interest on an overdue invoice or order will depend on the status of your customer and the contractual terms you have agreed that deal with any late payment. If you have a contract in place that contains a provision or clause for interest to be charged, then this should be sufficient to add interest to the overdue amount at the agreed rate.
If there is no specific contract in place with your customer that dictates interest charges, you may still be able to claim interest via legislation known as the Late Payment of Commercial Debts (Interest) Act 1998 if your customer is also a business (limited company, sole trader, partnership etc.). Late payment of commercial debts.
This late payment legislation permits you to charge 8% interest plus the Bank of England base rate on overdue debts owed by your business customers (B2B). You can begin charging interest as soon as payment becomes overdue, and if no payment date was documented or agreed payment is classed as late 30 days from the customer receiving your invoice or delivery of the service/product.
There are some exceptions and additional items that can be claimed as part of this legislation, so please read our full guide on claiming interest on unpaid invoices. Alternatively you may wish to instruct business debt recovery solicitors who will be able to calculate your late payment interest and compensation entitlement on your behalf. Business to consumer debts.
If the customer whose payment is overdue is an individual and not a business, there is no statutory right to charge interest on the amount. So, unless you have an agreed contract or terms of business in place that specifies additional charges will be made in the event of late payment, no interest is able to be added to the debt until court proceedings are started.
When dealing with debts incurred by consumers (and sole-traders) it is also important to comply with the Pre-Action Protocol for Debt Claims. Failure to do so before commencing court proceedings may result in sanctions being imposed on you, likely in relation to your court costs. Quick Reference - Interest on Debt Claims
* Based on statutory annual interest entitlement and the base rate, details correct as at May 2026.
Interest on personal debts.
If you are owed money as an individual such as through a private sale, shared bills or a personal loan, there is no entitlement to claim interest on the debt unless you have a signed contract or agreement that permits it.
For example, in the case of lending money ideally you will have documented the arrangement in a loan agreement which should have a provision for any interest and what occurs in the event of the borrower defaulting on their repayments. Without a written contract interest is not able to be added to a personal debt prior to court proceedings being started. Interest on court claims.
Regardless of the status of the debtor and the absence of a right to contractual interest, if you get to the stage of issuing a court claim to recover the debt, interest will often be able to be added to the amount owed.
Section 69 of the County Courts Act 1984 permits interest to be added to most non-commercial debts at the rate of 8% per year. This is a statutory interest rate and you can usually claim it from the date the debt was due up to the date you issue the claim. At the point of issuing court proceedings, other court fees and costs can also be added to the amount that is being claimed. However note that as with any other element of a claim, interest is awarded at the discretion of the court. The applicable interest is just one of the items that needs to be considered and calculated as part of a court claim for a debt. Therefore, it is always advisable to seek early legal advice if you are contemplating pursuing a substantial debt.
When you are owed money, hindsight can be a wonderful thing.
All too often in the rush to complete a business transaction or lending money to a friend in need, you won't think to put in place a legally binding agreement that formalises the arrangement beforehand. After all, you have every intention of holding up your end of the deal and so assume the other party will too. But if payment doesn't happen and your previous agreement starts turning into a dispute over what is owed, you may need to consider what legal avenues are open to you to get your money back. The success of any legal action will then depend on what evidence you can provide to show that the debt is owed. 
Are verbal agreements for money owed enforceable?
A contract between two parties does not have to be a signed document, contracts can be formed verbally.
While it is ideal to have a written agreement which outlines the a financial arrangement and the terms both parties have agreed to. If the same areas were covered in a conversation, then a legally binding contract may still have been formed. The key legal principles of a contract are:
If these principles have been met verbally, then a contract may have been formed which you can take legal action to enforce if the terms are breached. Can you take someone to court for owing you money?
Yes, but the 'burden of proof' will be on you as the Claimant to show that the amount you are claiming is due. Court should be your last resort in attempting to recover your money and so you should be confident that you have a strong case, sufficient evidence and follow the set pre-action procedure prior to issuing a claim (e.g. sending a letter before action, attempting negotiation etc.)
Ultimately the decision on who owes what will be down to a judge's ruling based on:
Owed money but no contract!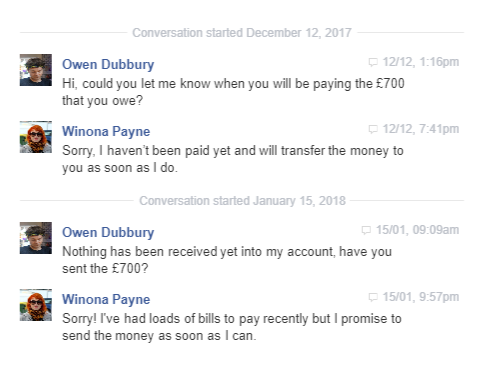 SMS or messages on social media can help prove a debt is owed.
In the absence of a written contract or agreement being in place, there are various other pieces of information that you may be able to secure which can provide evidence that the money is due.
Bounced cheque or returned direct debit While the use of cheques is diminishing, over 129 cheques are still issued every year. If your debtor has sent you a cheque that bounced or agreed to a direct debit that has been returned, it is often all the evidence that you need to prove a debt is owed. In law a cheque is considered a 'promise to pay' and so can be used as a clear admission that money is due. Unpaid invoices It is not uncommon for a business to invoice without a signed contract. Most businesses use invoices to request payment so providing copies and proof of them being issued to a customer or supplier will go a long way in proving that a debt is owed, even if they aren't directly attached to Terms of Business or a written terms. Furthermore, if you provided regular statements of the amounts owed and showing overdue, then these will also be useful as evidence. Evidence of chasing debts Once a payment is overdue you will have hopefully contacted the person or company to chase the debt. Emails, letters, texts or messages exchanged on social media (Facebook, WhatsApp, Snapchat etc.) can all be used to help prove a debt is owed and overdue. If the other party has responded to you apologising or asking for more time, then this admission will be extremely valuable in proving that they don't dispute that they actually owe the debt. So, it's important that you save or screenshot these messages in the event they are needed. Loaned money without a contract Without an I.O.U. or a loan agreement in place, proving that money provided to someone was a loan that needs to be repaid can be difficult. This is because often money given to friends, an ex, or family member is considered a gift and so isn't required to be paid back. Enforcing a verbal agreement that money is owed will hinge around providing evidence to show that the cash was transferred as a loan along with any repayments, e.g.
Witnesses to the arrangement When little or no documentation exists to prove a debt, having an independent witness to a verbal contract can be invaluable. For example - with a business transaction, did an employee take the order over the phone, deliver goods or perform a service where payment was verbally agreed with the customer? If money was lent to a friend, was another person present to witness the agreement of how/when they were going to pay you back? But even if an independent witness isn't available, you as a claimant can also present your version of events to the court in a written witness statement. Any witnesses may then need to attend court should the claim go all the way to a hearing. Debt disputes with no contract.
Without a written agreement, there should still be plenty of information that you can pull together to prove what you are owed. However, if the other party disputes the amount, or that any debt is owed at all, then you may have a fight on your hands that needs to be settled in court.
It will then be down to the evidence you can gather and how your claim is pleaded to convince a judge that you are entitled to the money owed in the absence of a legally binding written contract. So, obtaining legal advice on the evidence needed for a debt recovery claim and your prospects should be your starting point. |
About UsCatalyst Law are team of legal professionals with over 20 years' experience helping businesses and people with their legal problems. Categories
All
Follow us on:Archives
September 2026
|
 RSS Feed